Code: 08923897
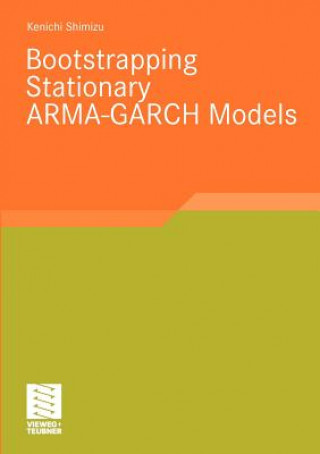
Bootstrapping Stationary ARMA-GARCH Models
by Kenichi Shimizu
Bootstrap technique is a useful tool for assessing uncertainty in statistical estimation and thus it is widely applied for risk management. Bootstrap is without doubt a promising technique, however, it is not applicable to all tim ... more


- Language:
 English
- Binding: Paperback
- Number of pages: 148
Publisher: Springer Fachmedien Wiesbaden, 2010
- More about this

51.33 €
RRP: 55.56 €
You save 4.23 €

In stock at our supplier
Shipping in 5 - 8 days
You might also like
-

your name. (light novel)
15.06 € -25 % -

Beste Freunde Język niemiecki 8 Zeszyt ćwiczeń
4.61 € -

The Girls
14.36 € -25 % -

Law of Recognition
11.54 € -25 % -

Premature Ejaculation - A relation with Anxiety
70.62 € -14 % -

Zábava se třpytivými samolepkami Prasátko Peppa
3.81 € -33 % -

Frontiers of Optical Spectroscopy
234.89 € -7 % -

Criminologia & Cinema: memória e verdade
70.22 € -

I Keep My Exoskeletons to Myself
20.29 € -25 % -

Impacto del USO de Las Tic
25.81 € -14 % -

Manuale del casaro. Latte e batteriologia. La coagulazione e la cagliata. Maturazione, stagionatura e difetti dei formaggi. La resa casearia. Ricotta
71.63 € -9 % -

Semantic Web-based Intelligent Geospatial Web Services
51.33 € -7 % -

Cuba El Legado de Fidel Castro
13.96 € -7 % -

Gesprache Zwischen Lehrpersonen Und Eltern
52.74 € -4 % -

The Testament of Peter the Great
44.80 € -7 % -

Forgotten Maryland Cocktails: 15 Historic Recipe Cards
7.43 € -22 % -

Legislación de Seguridad Social
80.77 € -

Uses of Psychoanalysis in Working with Children's Emotional Lives
125.58 € -

Sur la pierre du seuil
12.45 € -

Jump to It & Do It: Move Out Your Own Way and Walk by Faith
11.75 € -6 % -

Outsiders
35.46 € -
Quadra
24 € -

Glorias de la Alcarria : la razón de un centenario
13.05 € -

Les messageries maritimes à Hong Kong, 1918-1941
28.52 € -

Art of JAMA
144.27 € -

UNFAIR COMPETITION FROM THE PUBLIC SECTO
20.59 € -2 % -

Antiques De Rome
6.62 € -

Zoro's Field
17.87 € -24 % -

Lady with the Dog and Other Stories
19.38 € -10 % -

The Mirror and the Mask
13.76 € -9 % -

Classical Influences on European Culture, A.D. 1500-1700
59.37 € -

The History of Magic V2
43.49 € -2 % -

AP 164: Abalos and Herreros
45.20 € -

Lehrbuch + 4 Audio-CDs + 1 mp3-CD
69.01 € -11 % -

Re-Imagining South Asian Religions
211.08 € -

Rebel of the Family. [A Novel.] Vol. III
23.40 € -24 % -

Vuelo estático
31.54 € -

Encyclopedie Du Dessin, Principes Et Exemples Sur Toutes Les Parties de CET Art. (Ed.1811)
13.55 € -10 % -

Cours élémentaire de botanique, pour la classe de 5e
32.44 € -

Disciplinary Revolution
111.01 € -

Cat, Dog and Horse Lectures, and The Beyond
39.88 € -2 % -

Etude Industrielle Des Gites Metalliferes
30.33 € -

Windows NT 4.0 Server Security Guide
69.82 € -

LinkedIn - The World's Largest Professional Social Network - The Only Road to Success (published in Mandarin)
48.72 € -14 % -

Le monstre poilu et 3 autres histoires
19.28 € -

Das Leben des Noriker-Apostels St. Severin von seinem Schüler Eugippius
39.79 € -11 % -

Handbook of Zeolite Science and Technology
539.22 € -

Rethinking Geopolitics
87.50 € -

Songs My Mother Never Taught Me
13.36 € -9 %
Give this book as a present today
- Order book and choose Gift Order.
- We will send you book gift voucher at once. You can give it out to anyone.
- Book will be send to donee, nothing more to care about.
More about Bootstrapping Stationary ARMA-GARCH Models
You get 125 loyalty points
 Book synopsis

Bootstrap technique is a useful tool for assessing uncertainty in statistical estimation and thus it is widely applied for risk management. Bootstrap is without doubt a promising technique, however, it is not applicable to all time series models. A wrong application could lead to a false decision to take too much risk. Kenichi Shimizu investigates the limit of the two standard bootstrap techniques (the residual and the wild bootstrap) when these are applied to the conditionally heteroscedastic models, such as the ARCH and the GARCH models. The author shows that the wild bootstrap usually does not work well when one estimates conditional heteroscedasticity of Engle´s ARCH or Bollerslev´s GARCH models while the residual bootstrap works without problems. Together with the theoretical investigation simulation studies from the application of the proposed bootstrap methods are demonstrated.
Book details
Book category Books in English Mathematics & science Mathematics Probability & statistics
51.33 €
- Full title: Bootstrapping Stationary ARMA-GARCH Models
- Author: Kenichi Shimizu
- Language: English
- Binding: Paperback
- Number of pages: 148
- EAN: 9783834809926
- ISBN: 9783834809926
- ID: 08923897
- Publisher: Springer Fachmedien Wiesbaden
- Weight: 295 g
- Dimensions: 210 × 148 × 8 mm
- Date of publishing: 27. January 2010
Trending among others
-
Naked Statistics
12.95 € -28 % -
How to Lie with Statistics
10.84 € -25 % -
How to Lie with Statistics
13.25 € -28 % -
Foundations of the Theory of Probability: Second English
11.44 € -27 % -

Quantile Regression
137.23 € -
Fifty Challenging Problems in Probability with Solutions
8.73 € -24 % -
Probability Theory
146.28 € -
Measurement: A Very Short Introduction
9.43 € -30 % -
Theory of Open Quantum Systems
84.09 € -
Stochastic Processes and Filtering Theory
15.97 € -30 % -
Manga Guide To Statistics
18.58 € -25 % -
Elements of Statistical Learning
88.31 € -
Introduction to Probability, Second Edition
112.42 € -
Statistics: A Very Short Introduction
10.14 € -25 % -
First Course in Probability, Global Edition
93.03 € -
Probability: A Very Short Introduction
10.14 € -25 % -
Basic Probability Theory
17.17 € -24 % -
Introduction to Statistical Learning
60.27 € -9 % -
Statistical Physics
88.61 € -
Using Multivariate Statistics
82.18 € -14 % -
40 Puzzles and Problems in Probability and Mathematical Statistics
50.13 € -9 % -
The Fundamentals of People Analytics
41.08 € -7 % -
Probability Through Problems, 1
110.01 € -9 % -
Time-Series Forecasting
156.43 € -
Generalized Additive Models for Location, Scale, and Shape
69.72 € -
Robust Statistics 2e
143.77 € -10 % -
Cambridge International AS & A Level Mathematics Probability and Statistics 1 Student's Book
32.44 € -
Statistical Thermodynamics
8.03 € -25 % -
Pearson Edexcel International A Level Mathematics Statistics 2 Student Book
42.29 € -
Probability Theory
8.03 € -25 % -
Statistics Done Wrong
24.20 € -7 % -
Schaum's Outline of Probability and Statistics
19.28 € -25 % -
Statistics Workbook For Dummies, 2nd Edition with Online Practice
17.67 € -28 % -
Statistics For Dummies, 2nd Edition
18.58 € -25 % -
Manga Guide To Regression Analysis
17.57 € -31 % -
Theory That Would Not Die
14.36 € -25 % -
An Introduction to Statistical Learning
122.97 € -
Foundations of the Theory of Probability
6.52 € -27 % -
Collected Works of C.G. Jung
20.69 € -24 % -
Probability Theory
25.61 € -24 % -
Continued Fractions
7.32 € -25 % -
Elementary Decision Theory
17.17 € -24 % -
Foundations of Modern Probability
104.38 € -5 % -
Outlier Analysis
55.15 € -9 % -
Probability and Computing
69.32 € -5 % -
Probability Essentials
70.12 € -9 % -
Unfinished Game
23.80 € -
Probability and Statistics with R
153.41 € -
Philosophy and Probability
53.74 €
Collection points Bratislava a 13517 dalších
Copyright ©2008-26 najlacnejsie-knihy.sk All rights reservedPrivacyCookies

 27038 collection points
 Delivery 2.99 €
 02/210 210 99 (8-15.30h)
