Kód: 18624999
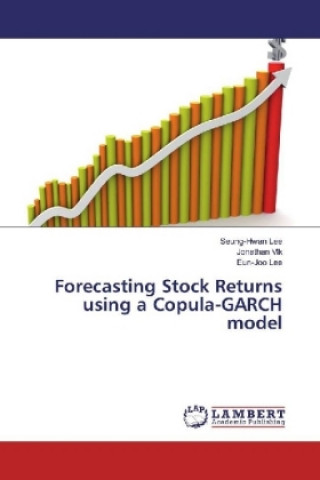
Forecasting Stock Returns using a Copula-GARCH model
Autor Seung-Hwan Lee, Jonathan Vlk, Eun-Joo Lee
Investigating dependence structures of stocks that are related to one another should be an important consideration in managing a stock portfolio, among other investment strategies. To capture various dependence features, we employ ... celý popis


- Jazyk:
 Angličtina
- Väzba: Brožovaná
- Počet strán: 60
Nakladateľ: LAP Lambert Academic Publishing, 2017
- Viac informácií o knihe

84.50 €
Bežne: 99.08 €
Ušetríte 14.57 €

Skladom u dodávateľa
Odosielame za 5 - 8 dní
Mohlo by sa vám tiež páčiť
-
Everything I Know About Love
11.25 € -23 % -

Culpa tuya (Culpables 2)
11.95 € -9 % -

Поехали! 1.1 Учебник. Начальный курс
38.68 € -11 % -

Last Second in Dallas
29.13 € -25 % -

Priziv
8.73 € -

Moses
14.56 € -6 % -

Krise demokracie
8.63 € -15 % -

Knights of Sidonia 6
24.91 € -11 % -

Urban Logistics
143.29 € -

Neptune the Heroic Horse
8.13 € -19 % -

Świat młodego odkrywcy mapa ścienna dla dzieci 580x380 mm
11.04 € -13 % -

Arabia Deserta
21.09 € -4 % -

Mein erstes lustiges Wimmelbuch: Viele Tiere
7.23 € -

Atlas of Head and Neck Surgery
217.05 € -5 % -

Passato
20.40 € -9 % -

Shadow Board Tool Sheets: White
43.30 € -

Les Mysteres de la Cour de Londres. Pauline
25.52 € -

The Complete Cookbook for Beginners: Essential Skills and Step-By-Step Techniques
18.58 € -25 % -
REGLAS PARA LA APLICACION DE LAS PENAS
45.71 € -

Fantasia
36.67 € -

Borsada Tek Basina
29.85 € -4 % -

Ned Myers, Or, a Life Before the Mast.
19.08 € -25 % -

Way to Be!: Manners Set
141.64 € -9 % -

Locked-In
19.49 € -

A Short Account of the Interest and Conduct of the Jamaica Planters: In an Address to the Merchants, Traders, and Liverymen of the City of London.
11.45 € -24 % -

Ariol 6
12.65 € -16 % -

Arabe Débutants (cahier d'exercices)
16.87 € -14 % -

Critical Notes on Plato's Politeia:
218.65 € -

Cornell University Hockey
19.89 € -22 % -

Sweet Home T09
19.28 € -

Interpreting Crimes in the Rome Statute of the International Criminal Court
48.73 € -

Luyia Nation
21.90 € -

The Trapper's Son
7.43 € -6 % -

History of the Inquisition of Spain; vol. 3
61.89 € -14 % -

ZOE Y EL TESORO DEL ZAR
20.69 € -

Les Sales Mômes
10.14 € -

Sultanetta
25.52 € -

The Shy Writer Reborn: An Introverted Writer's Wake-up Call
14.36 € -6 % -

Sol-Gel Handbook - Synthesis, Characterization , and Applications
548.18 € -15 % -

Endlich bin ich erloest
11.85 € -7 % -
Offshore Energy and Marine Spatial Planning
254.64 € -

Rylan and Henry
28.23 € -7 % -

Lone Wolf
12.55 € -7 % -

Mike and Me
43.91 € -
For The Love of Chaos
7.43 € -6 % -

L'Avenir Du Second Empire. La Politique Exterieure. Allemagne, Rome, Orient
18.78 € -1 % -

Wisconsin Talk
19.89 € -21 % -

How to Materialize What You Want With The Fxxxxxx Power
20.69 € -1 % -

Political Leadership and Collective Goods
103.30 € -

God Is...
10.44 € -6 % -
Metody issledovaniya prirodnyh yavlenij
37.17 € -14 % -

Mein erstes Buch uber Hadith
14.16 € -9 % -

Century, Volume 27
37.98 € -2 % -

Experiencing Led Zeppelin
60.59 € -

Computersimulation und rechnergestutzte Systemanalyse der leistungselektronischen Komponenten
42.50 € -11 % -

Trials of a Calm Waterfront
22.50 € -
Five Streams of Blessing: The Overview
9.94 € -7 % -

Kommunaler Einfluss in Europa
165.30 € -4 % -

Complete Writings of Charles Dudley Warner, Volume 12
33.45 € -1 % -

Proceedings of the 11th International Conference on Mechatronics and Control Engineering
173.74 € -7 % -
Black Intoxication
8.63 € -7 % -

Choice: Life or Death: Picking the Path of Life Over the Path of Death
14.36 € -7 % -

BABADADA black-and-white, Schwiizerdutsch mit Artikeln - Tiếng Việt, s Bildwoerterbuech - từ điển tranh minh họa
6.72 € -

Psychology and Psychotherapy
21.81 € -

Greek Orators IV: Andocides
186.40 € -

Perspectivas de la agricultura familiar
48.65 € -14 % -

Mixed Up
11.75 € -6 % -

Die Wirkung einer Internationalisierung des Yen auf die japanischen Finanzmaerkte, die japanische Geldpolitik und die Usancen der Fakturierung
175.95 € -

Joint Professional Military Education 1999
17.07 € -10 % -

1001 secrets de chats
15.26 €
Darujte túto knihu ešte dnes
- Objednajte knihu a vyberte Zaslať ako darček.
- Obratom obdržíte darovací poukaz na knihu, ktorý môžete ihneď odovzdať obdarovanému.
- Knihu zašleme na adresu obdarovaného, o nič sa nestaráte.
Viac informácií o knihe Forecasting Stock Returns using a Copula-GARCH model
Nákupom získate 206 bodov
 Anotácia knihy

Investigating dependence structures of stocks that are related to one another should be an important consideration in managing a stock portfolio, among other investment strategies. To capture various dependence features, we employ copula. Financial time series data is typically characterized by volatility clustering of returns that influences an estimate of a stock's future price. To deal with the volatility and dependence of stock returns, this book provides procedures of combining a copula with a GARCH model. Using the copula-GARCH approach that describes the tail dependences of stock returns, we carry out Monte Carlo simulations to predict a company's movements in the stock market. The procedures are illustrated in two technology stocks, Apple and Samsung.
Parametre knihy
84.50 €
- Celý názov: Forecasting Stock Returns using a Copula-GARCH model
- Autor: Seung-Hwan Lee, Jonathan Vlk, Eun-Joo Lee
- Jazyk: Angličtina
- Väzba: Brožovaná
- Počet strán: 60
- EAN: 9783659233579
- ID: 18624999
- Nakladateľ: LAP Lambert Academic Publishing
- Hmotnosť: 107 g
- Rozmery: 220 × 150 × 5 mm
- Rok vydania: 2017
Obľúbené z iného súdka
-
Threshing Day (Limited Deluxe Edition)
19.49 € -34 % -
Cozy Countdown: An Advent Coloring Book Bundle
22.10 € -25 % -
Court of Thorns and Roses 6
17.07 € -28 % -
Murdoku
14.96 € -21 % -
The Mirror of Infinite Endings
17.98 € -17 % -
The Long-Lived King: An Original The Owl House Graphic Novel
19.69 € -9 % -
White Nights
3.61 € -31 % -
Trust Fall
10.04 € -29 % -
I'll Believe in Anything. The Making of Heated Rivalry Season 1
20.89 € -29 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 9
19.28 € -22 % -
Threshing Day (Wing and Claw Collection)
18.58 € -25 % -
Once Upon a Broken Heart Collector's Edition
26.92 € -29 % -

A Conspiracy of Charming Monsters
17.17 € -25 % -
Berserk Deluxe Volume 1
54.06 € -
Fourth Wing
24.01 € -25 % -

A Conspiracy of Charming Monsters
16.57 € -21 % -
21 Days of Fear
17.78 € -22 % -
East of Eden
12.35 € -28 % -
Lord of Mysteries, Vol. 4: The Faceless, Part I
16.97 € -15 % -
Murdoku Volume 2: Back in Time
13.66 € -29 % -
Iron Flame
25.01 € -24 % -

Chainsaw Man, Vol. 22
10.04 € -20 % -
Berserk Deluxe Volume 3
35.26 € -27 % -
Protocols
16.57 € -
The Art of Gravity Falls
37.78 € -23 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 2
19.18 € -22 % -
How to Win at Chess, Next Level
27.53 € -7 % -
Witch Hat Atelier: Grimoire Edition 1
36.27 € -25 % -
Penguin Readers Level 4: The Adventures of Sherlock Holmes (ELT Graded Reader)
10.94 € -5 % -
Witch Hat Atelier: Grimoire Edition 2
35.26 € -30 % -
The Count of Monte Cristo
9.34 € -30 % -

Witch Hat Atelier: Grimoire Edition 3
36.17 € -25 % -
The Mirror of Infinite Endings
21.90 € -29 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 1
19.18 € -22 % -
Murdle: Volume 1
12.95 € -29 % -

Murdoku Volume 3: Around the World
14.36 € -25 % -
Berserk Deluxe Volume 2
36.97 € -31 % -
Escape Me Deluxe Limited Edition
19.89 € -22 % -

JoJo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 3
19.18 € -22 % -
The Courage To Be Disliked
10.64 € -13 % -

The Guy She Was Interested in Wasn't a Guy at All, Vol. 1
15.06 € -29 % -

Spooky Cutie
8.13 € -29 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 8
18.28 € -26 % -
JoJo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 4
19.18 € -22 % -

The Guy She Was Interested in Wasn't a Guy at All, Vol. 4
15.06 € -25 % -
Berserk Deluxe Volume 4
47.32 € -11 % -
What Happened Yesterday
16.07 € -26 % -
Yesteryear
16.17 € -12 % -
Onyx Storm
14.76 €
Collection points Bratislava a 13652 dalších
Copyright ©2008-26 najlacnejsie-knihy.sk All rights reservedPrivacyCookies

 27308 collection points
 Delivery 2.99 €
 02/210 210 99 (8-15.30h)
