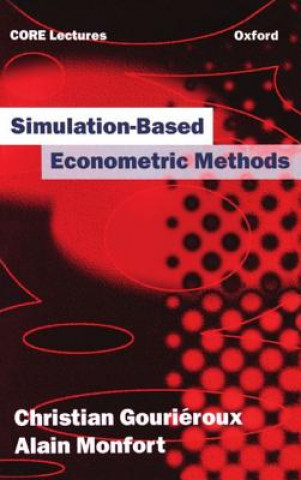
Code: 04477410
Simulation-based Econometric Methods
by Gourieroux
This book introduces a new generation of statistical econometrics. After linear models leading to analytical expressions for estimators, and non-linear models using numerical optimization algorithms, the availability of high- spe ... more


- Language:
 English
- Binding: Hardback
- Number of pages: 184
Publisher: Oxford University Press, 1997
- More about this


You might also like
-

Spielesammlung 50 Spielmöglichkeiten Paw Patrol
16.10 € -

grande viaggio della piccola Angelica
30.40 € -9 % -

Analogia
13.80 € -24 % -

Sweetpea
14.70 € -9 % -

Alex Rider 02: Gemini-Project
8.99 € -10 % -

МАЙНКРАФТ своими руками. 15 веселых и простых проектов
6.39 € -9 % -

#WhyIMarch: What You Can Do to #Resist the Trump Agenda
8.89 € -6 % -

Durham Cathedral ... Third Edition, with Plan and Illustrations.
18.90 € -2 % -

Colleen's Pocket Posh Journal, Tulip
7.19 € -24 % -

Materiais Educativos e Estilos de Aprendizagem
35.30 € -14 % -

Het Tetraglotton van 1562, 2
108.03 € -4 % -

Lärobok i rumänska för nybörjare
38.41 € -7 % -

The Theory of Functional Grammar
73.92 € -

Sous le soleil de kheops a2
14.80 €
Give this book as a present today
- Order book and choose Gift Order.
- We will send you book gift voucher at once. You can give it out to anyone.
- Book will be send to donee, nothing more to care about.
More about Simulation-based Econometric Methods
You get 343 loyalty points
 Book synopsis

This book introduces a new generation of statistical econometrics. After linear models leading to analytical expressions for estimators, and non-linear models using numerical optimization algorithms, the availability of high- speed computing has enabled econometricians to consider econometric models without simple analytical expressions. The previous difficulties presented by the presence of integrals of large dimensions in the probability density functions or in the moments can be circumvented by a simulation-based approach. After a brief survey of classical parametric and semi-parametric non-linear estimation methods and a description of problems in which criterion functions contain integrals, the authors present a general form of the model where it is possible to simulate the observations. They then move to calibration problems and the simulated analogue of the method of moments, before considering simulated versions of maximum likelihood, pseudo-maximum likelihood, or non-linear least squares. The general principle of indirect inference is presented and is then applied to limited dependent variable models and to financial series.
Book details
Book category Books in English Economics, finance, business & management Economics Econometrics
140.05 €
- Full title: Simulation-based Econometric Methods
- Author: Gourieroux
- Language: English
- Binding: Hardback
- Number of pages: 184
- EAN: 9780198774754
- ISBN: 0198774753
- ID: 04477410
- Publisher: Oxford University Press
- Weight: 434 g
- Dimensions: 236 × 160 × 19 mm
- Date of publishing: 09. January 1997
Trending among others
-

Macroeconometrics
53.41 € -25 % -

Analysis of Financial Time Series 3e
142.05 € -10 % -

Econometrics in Theory and Practice
99.63 € -9 % -

Algorithmic and High-Frequency Trading
82.52 € -

Capital Returns
79.92 € -

Trades, Quotes and Prices
95.83 € -

Introductory Econometrics
113.14 € -

Undercover Economist, Revised and Updated Edition
22.80 € -25 % -

Introduction to Econometrics, Global Edition
114.14 € -

Mostly Harmless Econometrics
54.91 € -11 % -

Algorithmic Trading and Quantitative Strategies
187.77 € -

Time Series Analysis
87.43 € -9 % -

Statistics
145.85 € -

Econometrics For Dummies
21.50 € -24 % -

Who Gets What - And Why
10.29 € -27 % -

First Course in Quantitative Finance
73.62 € -

Econometrics
79.12 € -11 % -

Schaum's Outline of Statistics and Econometrics, Second Edition
25.70 € -18 % -

Econometric Analysis of Cross Section and Panel Data
152.15 € -

Convex Optimization
104.23 € -
Introduction to Time Series and Forecasting
89.63 € -9 % -

Mastering 'Metrics
39.31 € -6 % -

Introduction to Quantitative Finance
63.12 € -

Guide to Econometrics 6e
54.21 € -

Essential Mathematics for Economics and Business 4e
78.82 € -4 % -

Skeptical Environmentalist
53.81 € -

Standard Deviations
14.50 € -

Minitab Demystified
35.30 € -18 % -

Using Excel for Principles of Econometrics, Fourth Edition
43.81 € -

Tyranny of Metrics
28.40 € -

Energy Trading and Risk Management
112.04 € -7 % -

Computational Actuarial Science with R
77.92 € -

Bayesian Econometrics
74.42 € -

Experimental Economics
50.91 € -

Technical Analysis of Stock Trends
165.16 € -

Stochastic Volatility Modeling
139.75 € -

Econometric Modelling with Time Series
101.63 € -

Time Series Econometrics
109.53 € -9 % -

Introductory Econometrics
110.94 € -

Introduction to Econometrics 4e
76.92 € -

Mathematics for Finance, Business and Economics
85.72 € -

Martingale Methods in Financial Modelling
122.14 € -7 % -

Financial Analytics with R
90.23 € -

Essentials of Excel, Excel VBA, SAS and Minitab for Statistical and Financial Analyses
159.26 € -9 % -
Course in Econometrics
108.73 € -

Forecasting, Structural Time Series Models and the Kalman Filter
53.81 € -
Panel Data Econometrics with R
98.33 € -1 % -

Reproducible Econometrics Using R
83.22 € -

Time Series: Theory and Methods
145.35 €
Collection points Bratislava a 13474 dalších
Copyright ©2008-26 najlacnejsie-knihy.sk All rights reservedPrivacyCookies

 26952 collection points
 Delivery 2.99 €
 02/210 210 99 (8-15.30h)
