Code: 32807202
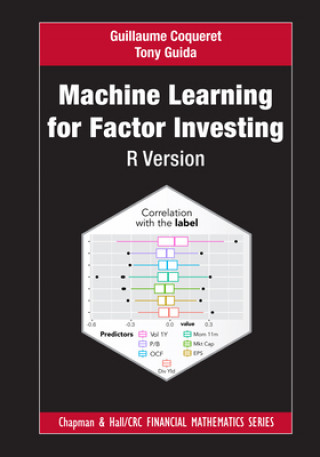
Machine Learning for Factor Investing: R Version
by Guillaume Coqueret, Tony Guida
Machine learning (ML) is progressively reshaping the fields of quantitative finance and algorithmic trading. ML tools are increasingly adopted by hedge funds and asset managers, notably for alpha signal generation and stocks selec ... more


- Language:
 English
- Binding: Hardback
- Number of pages: 321
Publisher: Taylor & Francis Ltd, 2020
- More about this

290.68 €
RRP: 290.71 €
You save 0.04 €
Availability:
50/50 We think title might be available. Upon your order we will do our best to get it within 6 weeks.
We search the world
You might also like
-
PET SEMATARY
14.06 € -29 % -
Beyond The Basic Stuff With Python
28.54 € -29 % -

Abarat Days of Magic, Nights of War
12.55 € -26 % -

Journal d'un dégonflé 09. Un loooong voyage
15.77 € -

Verbal Behavior
16.47 € -

Occupational Therapy Activities for Kids: 100 Fun Games and Exercises to Build Skills
15.77 € -25 % -

Emma
14.56 € -31 % -
Иллюстрированный атлас мира (в новых границах)
29.44 € -11 % -

Practical Antenna Design 140-150 MHz VHF Transceivers Third Edition
19.59 € -7 % -
Children of the Corn
28.74 € -10 % -
PROJECT MIND CONTROL
22.10 € -25 % -
Head First Statistics
32.66 € -25 % -

Advanced Techniques in Canine and Feline Neurosurg ery
180.01 € -9 % -
Beatles: The Beatles 1962-1966 (Red) LP
95.08 € -

Valiant: A Modern Faerie Tale
18.48 € -9 % -

Star Wars: The Mandalorian
5.72 € -18 % -
Chivalry of a Failed Knight 04
6.82 € -9 % -

Erinnerungen Des Posener Domherren Albert Steuer
51.57 € -1 % -
Nuclear Auditing Handbook
139.20 € -2 % -
When You Are Mine
13.66 € -25 % -
Advanced Automotive Fault Diagnosis
184.94 € -

Die Maklerprovision bei Hauptvertragsstörungen und Pflichtverletzungen
38.79 € -
Ecology and Contemporary Nordic Cinemas
52.96 € -

Directory of Libraries in Canada 2009
447.86 € -
Tangletree Mysteries: Peggy & Stu Hear Something Strange
9.64 € -25 % -

BABADADA, Uzbek (in cyrillic script) - Espanol de Mexico, visual dictionary (in cyrillic script) - diccionario visual
27.43 € -7 % -

Why Do We Get Married?
17.88 € -
Devine ? J'apprends les chats
7.83 € -

Ein Motiv aus dem Kalender Côte de Granit Rose, einmalige Küstenregion der Bretagne (Puzzle)
33.86 € -
Civil War Alabama
34.47 € -4 % -

Improvisational Negotiation
33.56 € -10 % -

American Music For Guitar & Piano
16.68 € -
Voyage interdit
20.49 € -
Lebensmittelintoleranzen leicht gemacht
8.23 € -8 % -
Ventilation Performance Indices with Elevated Air Movement for Health, Thermal Comfort, and Energy Efficiency
204.43 € -7 % -

Framtidsmannen
14.36 € -7 % -
THE LEGEND OF S. EOLINDE: A POEM, BY R.L
28.84 € -2 % -
Encyclopedia of the Lories LTD ED
361.03 € -15 % -

Secret Kingdom: Jewel Cavern
6.52 € -25 % -

Gutsy Girls Go for Science: Programmers: With STEM Projects for Kids
18.89 € -9 % -

¡TAM TAM!:RITMO EN LA SELVA
20.90 € -2 % -
Etat-providence et les jeunes
17.08 € -12 % -
Supplementum Coelifodinae
207.05 € -1 % -
Smithsonian Contributions to Knowledge.
33.46 € -2 % -

Comptabilité publique territoriale Nathan Sup
27.33 € -

Collier en argent 8 pierres serties Labradorite
16.68 € -

wonderland of the Eastern Congo
25.22 € -18 % -
La route du paradis ou la dévoration des ciels
6.72 € -
Amelia Frump & Her Peanut Butter Loving, Overactive Imagination is Cooking Up a Peanut Butter Storm
18.08 € -7 % -
Magistri Vacarii Summa De Matrimonio
26.12 € -2 % -

Stroke of Death
18.69 € -7 % -

Wisdom of the Cross
38.29 € -25 % -
Story of Lady Juliana Harley, a Novel. in Letters. by Mrs. Griffith. in Two Volumes. ... Volume 1 of 2
15.57 € -25 % -
"The Battle Raged... With Terrible Fury: " Battlefield Archaeology of Pea Ridge National Military Park
14.36 € -6 % -

Parathyroid Gland Disorders
155.08 € -9 % -
John Howie of Lochgoin: His Forebears and His Works; 1909
14.16 € -2 % -
Season of Mists
9.74 € -

Book of Evidence
35.97 € -24 % -
Satana, la chiesa, il mondo
29.64 € -9 % -
Goethe Yearbook 10
105.73 € -

Common Issues We Face in Life
17.88 € -25 % -
Curious, If True: Strange Tales
13.86 € -7 % -

Type A Behavior: Its Diagnosis and Treatment
90.15 €
Give this book as a present today
- Order book and choose Gift Order.
- We will send you book gift voucher at once. You can give it out to anyone.
- Book will be send to donee, nothing more to care about.
Availability alert
Enter your e-mail address and once book will be available,
we will send you a message. It's that simple.
More about Machine Learning for Factor Investing: R Version
You get 708 loyalty points
 Book synopsis

Machine learning (ML) is progressively reshaping the fields of quantitative finance and algorithmic trading. ML tools are increasingly adopted by hedge funds and asset managers, notably for alpha signal generation and stocks selection. The technicality of the subject can make it hard for non-specialists to join the bandwagon, as the jargon and coding requirements may seem out of reach. Machine Learning for Factor Investing: R Version bridges this gap. It provides a comprehensive tour of modern ML-based investment strategies that rely on firm characteristics.
The book covers a wide array of subjects which range from economic rationales to rigorous portfolio back-testing and encompass both data processing and model interpretability. Common supervised learning algorithms such as tree models and neural networks are explained in the context of style investing and the reader can also dig into more complex techniques like autoencoder asset returns, Bayesian additive trees, and causal models.
All topics are illustrated with self-contained R code samples and snippets that are applied to a large public dataset that contains over 90 predictors. The material, along with the content of the book, is available online so that readers can reproduce and enhance the examples at their convenience. If you have even a basic knowledge of quantitative finance, this combination of theoretical concepts and practical illustrations will help you learn quickly and deepen your financial and technical expertise.
Book details
290.68 €
- Full title: Machine Learning for Factor Investing: R Version
- Author: Guillaume Coqueret, Tony Guida
- Language: English
- Binding: Hardback
- Number of pages: 321
- EAN: 9780367473228
- ISBN: 0367473224
- ID: 32807202
- Publisher: Taylor & Francis Ltd
- Weight: 790 g
- Dimensions: 254 × 178 mm
- Date of publishing: 01. September 2020
Trending among others
-
Threshing Day (Limited Deluxe Edition)
18.69 € -30 % -
Murdoku
14.97 € -21 % -
The Mirror of Infinite Endings
14.66 € -25 % -
The Long-Lived King: An Original The Owl House Graphic Novel
19.69 € -18 % -
White Nights
4.51 € -14 % -
Court of Thorns and Roses 6
15.67 € -30 % -
The Art of Gravity Falls
37.68 € -23 % -
21 Days of Fear
16.68 € -27 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 9
19.19 € -22 % -
I'll Believe in Anything. The Making of Heated Rivalry Season 1
18.69 € -30 % -
Trust Fall
10.04 € -29 % -
Lord of Mysteries, Vol. 4: The Faceless, Part I
16.98 € -15 % -
Berserk Deluxe Volume 1
38.99 € -27 % -
The Mirror of Infinite Endings
19.29 € -37 % -
Fourth Wing
23.91 € -27 % -
Berserk Deluxe Volume 3
55.37 € -
Penguin Readers Level 4: The Adventures of Sherlock Holmes (ELT Graded Reader)
10.95 € -
Protocols
14.77 € -29 % -
Berserk Deluxe Volume 2
36.88 € -31 % -
Witch Hat Atelier: Grimoire Edition 1
35.57 € -29 % -
Iron Flame
24.92 € -24 % -
Witch Hat Atelier: Grimoire Edition 2
35.17 € -27 % -
Murdoku Volume 2: Back in Time
14.97 € -21 % -
The Count of Monte Cristo
13.76 € -9 % -
Protocols
16.47 € -19 % -
Cozy Countdown: An Advent Coloring Book Bundle
21.70 € -28 % -
East of Eden
12.76 € -26 % -
Escape Me Deluxe Limited Edition
19.29 € -25 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 8
18.18 € -26 % -
The Courage To Be Disliked
10.64 € -13 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 2
19.19 € -22 % -
Absolute Batman Vol. 3
19.29 € -8 % -
Once Upon a Broken Heart Collector's Edition
26.73 € -29 % -
Kid's Box New Generation Level 2 Activity Book with Digital Pack British English
10.74 € -9 % -
What Happened Yesterday
15.97 € -27 % -
Berserk Deluxe Volume 4
43.41 € -18 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 1
19.19 € -22 % -
Protocols
29.44 € -26 % -
Pokémon Deluxe Character Guide
41 € -28 % -
Dungeon Crawler Carl
11.45 € -29 % -
Berserk Deluxe Volume 5
54.87 € -
Kid's Box New Generation Level 1 Activity Book with Digital Pack British English
11.15 € -5 % -
The Emperor's Enemy (Deluxe Limited Edition)
24.21 € -29 % -
Yesteryear
16.07 € -12 % -
Fruit Fly
16.68 € -27 % -
How to Win at Chess, Next Level
26.32 € -11 % -
Restitution
9.84 € -27 % -
Murdle: Volume 1
14.26 € -21 % -
How Lucky Am I?
19.49 € -26 %
Collection points Bratislava a 13217 dalších
Copyright ©2008-26 najlacnejsie-knihy.sk All rights reservedPrivacyCookies

 26438 collection points
 Delivery 2.99 €
 02/210 210 99 (8-15.30h)
