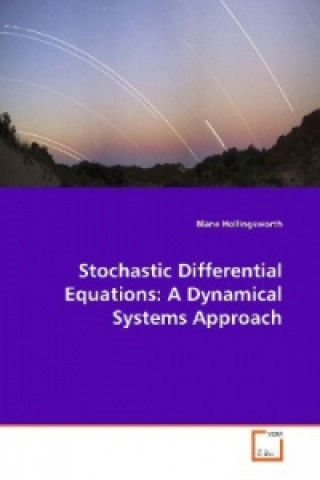
Code: 06821422
Stochastic Differential Equations: A Dynamical Systems Approach
by Blane Hollingsworth
The relatively new subject of stochastic differential§equations has§increasing importance in both theory and§applications. The subject§draws upon two main sources, probability/stochastic§processes and§differential equations/dynami ... more


- Language:
 English
- Binding: Paperback
- Number of pages: 136
Publisher: VDM Verlag Dr. Müller, 2009
- More about this


You might also like
-
Diary of a Wimpy Kid Partypooper Book 20
11.44 € -22 % -
The Dragon Reborn
17.16 € -25 % -
C Programming Language: The Ultimate Beginner's Guide
9.93 € -7 % -

Fifty Shades of Grey
10.53 € -26 % -

Učebnice sebelásky
13.14 € -15 % -
A Rumor of War: The Classic Vietnam Memoir
16.46 € -25 % -
Empirical Structural Design for Architects, Engineers and Builders
64.75 € -
Pravomil
13.85 € -6 % -

Fiche de lecture Le Mythe de Sisyphe de Albert Camus (Analyse litteraire de reference et resume complet)
5.91 € -

Za plotem
9.23 € -5 % -
Thonet
43.37 € -11 % -

American Constitution and the Debate over Originalism
35.13 € -

Esto es agua : algunas ideas, expuestas en una ocasión especial, sobre cómo vivir con compasión
12.74 € -1 % -

La qu?te de l'identité personnelle dans les romans de Siegfried Lenz et de Michel Tournier
21.68 € -24 % -

El corazón de hojalata - 2
29.11 € -

Advanced Antenna Systems for 5G Network Deployments
149.50 € -

French Tales of Alien Encounters
28.81 € -2 % -
Miś Pracuś. Zwierzęta. Moje pierwsze naklejki
3.60 € -24 % -
Manifest Tyranny
13.65 € -
Collections Upon the Lives of the Reformers and Most Eminent Ministers of the Church of Scotland; Volume 2
33.43 € -1 % -

Georg Baselitz: Peintre - Graveur IV
81.42 € -19 % -

Happy Street: 2: CDs (2)
27.70 € -5 % -
Varieties of Post-communist Capitalism
32.82 € -20 % -
The American Rose Annual / American Rose Society
31.62 € -1 % -
Addressing Regulatory Gaps in Relation to the Environmental Issues Arising from Offshore Oil and Gas Activities in the Arctic
42.46 € -14 % -
Historiae
12.64 € -25 % -

Groups, Representations and Physics
109.74 € -

Economics and Policies of Integration - a Finnish Perspective
102.21 € -7 % -
Candle Magic Wicca Spells: Solitary Practitioner Guide
11.74 € -6 % -

War at Saber Point
35.25 € -9 % -
Differential Equations: A Dynamical Systems Approach
50.09 € -9 % -
Los cuatro jinetes del Apocalipsis
15.45 € -7 % -

Les Godillots - tome 04
19.07 € -

Bagnes, Prisons Et Criminels. IV (Ed.1836)
28.11 € -

Golden Fox
18.77 € -22 % -
On the Heels of Ignorance
40.96 € -
The Woodsman of Anglia: Eriswell
18.67 € -6 % -
Désiré Savalle, ingénieur constructeur, notice biographique
12.34 € -1 % -
These Pour La Licence. Faculte de Droit de Strasbourg Soutenue Le Mardi 22 Aout 1854
15.05 € -2 % -

Asian Thought on China's Changing International Relations
57.12 € -
Women Are Like Cats and Men Like Dogs
16.06 € -6 % -
Rechnen mit Rico Schnabel 1, Heft 2 - Rechnen im Zahlenraum bis 10
7.62 € -

Differential Equations: A Dynamical Systems Approach
169.78 € -9 % -

Yasmina 3
15.55 € -
Walking the Brittany Coast
12.04 € -15 % -

Whose Feet Are These?
19.27 € -

Space Environment Well-being
239.47 € -14 % -

Walter Cecchinel, itinéraire(s) d’un outsider
30.11 € -
À la table de May
41.16 € -

The Nature and Aim of Theosophy
21.48 € -2 % -

Financial Adviser
20.67 € -25 % -

Die Geschichte Des Tom Jones, Teil 2
11.64 € -10 % -
Something About the Author
375.68 € -

Dieta Paleolitica Completa Per Principianti: Alimenti Consentiti E Benefici, Alimenti Proibiti, Alimenti Proibiti, Imparare Le Basi E La Storia Di Que
8.22 € -6 % -

Questions I Want to Ask You
13.95 € -26 % -
Full Salvation: As Seen In Bunyan's Pilgrim's Progress (1884)
27 € -1 % -
Quantum Continuous Variables
76.40 € -

Urbanization and the Migrant in British Cinema
58.23 € -4 % -

Transforming Urban Transport
55.12 € -
Histoire Parlementaire de France Tome 3
37.14 € -

Florida für Einwanderer
9.03 € -9 % -
Voice of the City, Further Stories of the Four Million
23.19 € -

Warum seid Ihr nicht ausgewandert?
19.27 € -3 % -
Mollami! Educare i figli adolescenti e trovare la giusta distanza per farli crescere
17.96 € -
Differential Equations: A Dynamical Systems Approach
159.84 € -9 % -
Hat das Auslaufen der Lock-up Periode einen Einfluss auf die Aktienmarktentwicklung?
24.89 € -11 % -

Tra alti e bassi. Charlotte
13.75 € -

Strannaq kniga
37.74 € -14 % -

Rocks of Prehistory: the Gumlog Creek Rockshelter
17.86 € -1 % -
Italian Letters V1 and V2
20.57 € -2 % -
Leisure Time Kids Activity Book! Connect the Dots
8.42 € -2 % -
The Essential Diet for Fatty Liver: Nutrition Guide and Recipes to Heal Your Body
12.94 € -25 % -
Power Quality
136.75 € -14 % -

Jetzt reicht's mir aber! - Hörbuch
20.77 € -16 % -

Podstawy refrakcji oka i korekcji wad wzroku
37.14 € -
Differential Equations: A Dynamical Systems Approach
73.99 € -9 % -

Bread of Life
17.96 € -10 % -
The Science Religion and Reality
37.95 € -2 % -
Oeuvres Completes d'Etienne Jouy. T27
33.23 € -

Wycliffe And The Redhead
24.19 € -
College in Three Years
10.13 € -24 % -

CIRCLE OF DEATH UAB CD
29.21 € -26 % -
Civil War Veterans of Perry County, Indiana
29.41 € -

Monumental Matters
114.76 €
Give this book as a present today
- Order book and choose Gift Order.
- We will send you book gift voucher at once. You can give it out to anyone.
- Book will be send to donee, nothing more to care about.
More about Stochastic Differential Equations: A Dynamical Systems Approach
You get 145 loyalty points
 Book synopsis

The relatively new subject of stochastic differential§equations has§increasing importance in both theory and§applications. The subject§draws upon two main sources, probability/stochastic§processes and§differential equations/dynamical systems. There§exists a significant§``culture gap" between the corresponding research§communities. The§objective of the dissertation project is to present a§concise yet§mostly self-contained theory of stochastic§differential equations§from the differential equations/dynamical systems§point of view,§primarily incorporating semigroup theory and§functional analysis§techniques to study the solutions. Prerequisites from§probability/stochastic processes are developed as needed.§ For continuous-time stochastic§processes whose random variables are (Lebesgue)§absolutely§continuous, the Fokker-Planck equation is employed to§study the§evolution of the densities, with applications to§predator-prey§models with noisy coefficients.
Book details
59.33 €
- Full title: Stochastic Differential Equations: A Dynamical Systems Approach
- Author: Blane Hollingsworth
- Language: English
- Binding: Paperback
- Number of pages: 136
- EAN: 9783639126488
- ID: 06821422
- Publisher: VDM Verlag Dr. Müller
- Weight: 219 g
- Dimensions: 220 × 150 × 8 mm
- Published: 2009
Trending among others
-
Threshing Day (Limited Deluxe Edition)
19.37 € -34 % -
Murdoku
14.95 € -21 % -
The Mirror of Infinite Endings
14.65 € -31 % -
Cozy Countdown: An Advent Coloring Book Bundle
22.08 € -25 % -
The Long-Lived King: An Original The Owl House Graphic Novel
19.67 € -29 % -
Court of Thorns and Roses 6
15.65 € -30 % -
White Nights
4.51 € -14 % -
I'll Believe in Anything. The Making of Heated Rivalry Season 1
18.67 € -30 % -
Trust Fall
10.93 € -19 % -
The Art of Gravity Falls
37.64 € -28 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 9
19.17 € -22 % -
21 Days of Fear
16.66 € -27 % -
Berserk Deluxe Volume 1
38.95 € -27 % -
Lord of Mysteries, Vol. 4: The Faceless, Part I
16.96 € -15 % -
The Mirror of Infinite Endings
21.78 € -29 % -
Fourth Wing
23.89 € -27 % -
Iron Flame
24.89 € -24 % -
Berserk Deluxe Volume 3
55.42 € -
Witch Hat Atelier: Grimoire Edition 2
35.13 € -30 % -
Murdoku Volume 2: Back in Time
13.75 € -29 % -
East of Eden
12.74 € -26 % -
Once Upon a Broken Heart Collector's Edition
26.70 € -29 % -
Penguin Readers Level 4: The Adventures of Sherlock Holmes (ELT Graded Reader)
10.93 € -2 % -
Berserk Deluxe Volume 2
36.84 € -31 % -
The Count of Monte Cristo
13.75 € -9 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 2
19.17 € -22 % -
Escape Me Deluxe Limited Edition
19.27 € -25 % -
Protocols
16.46 € -
Witch Hat Atelier: Grimoire Edition 1
34.23 € -32 % -
Chainsaw Man, Vol. 22
9.43 € -25 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 1
19.17 € -22 % -
Protocols
14.75 € -29 % -
Protocols
29.41 € -27 % -
How to Win at Chess, Next Level
26.40 € -11 % -
Jojo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 8
18.16 € -26 % -
The Courage To Be Disliked
10.63 € -13 % -
Pokémon Deluxe Character Guide
40.96 € -28 % -
Absolute Batman Vol. 3
19.27 € -8 % -
Berserk Deluxe Volume 4
43.37 € -19 % -
Yesteryear
16.06 € -12 % -
Murdle: Volume 1
12.94 € -29 % -
JoJo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 3
19.17 € -22 % -
What Happened Yesterday
15.96 € -27 % -
The Emperor's Enemy (Deluxe Limited Edition)
24.29 € -29 % -
Fruit Fly
16.66 € -27 % -
JoJo's Bizarre Adventure: Part 7--Steel Ball Run, Vol. 7
18.16 € -26 % -
Kid's Box New Generation Level 2 Activity Book with Digital Pack British English
10.73 € -9 % -
Restitution
9.83 € -27 % -
The Guy She Was Interested in Wasn't a Guy at All, Vol. 1
13.55 € -31 %
Osobný odber Bratislava a 13357 dalších
Copyright ©2008-26 najlacnejsie-knihy.sk Všetky práva vyhradenéSúkromieCookies

 25 miliónov titulov
 Vrátenie do mesiaca
 02/210 210 99 (8-15.30h)
